
A standard homeowners policy may cover several common disaster-related losses, but it does not cover every natural hazard. For households in Vestavia Hills, AL, the most important distinction is usually between wind-related damage, which is often covered, and flood damage, which generally requires separate insurance.
The answer depends on the policy form, exclusions, deductibles, coverage limits, and endorsements shown on the declarations page. A policy that satisfies a mortgage lender may still leave significant gaps after a major storm.
What natural disasters does homeowners insurance usually cover?
Most homeowners policies cover the home and personal property against listed risks or, under broader policy forms, losses that are not specifically excluded. Common covered causes of loss may include:
- Windstorm and tornado damage
- Hail damage
- Lightning and fire
- Falling trees, subject to policy conditions
- Damage from a vehicle
- Certain types of sudden and accidental water damage
- Theft or vandalism following a covered event
Alabama Department of Insurance materials identify windstorm and hail as common covered perils under basic homeowners policy forms. A typical policy also may include coverage for the dwelling, attached structures, personal property, and additional living expenses if the home becomes uninhabitable after a covered loss. ([insurance.alabama.gov](https://www.insurance.alabama.gov/PDF/Consumers/NaturalDisastersGuide.pdf?utm_source=openai))
Coverage is not automatic simply because a storm occurred. The cause of damage matters. For example, wind that tears open a roof may be covered, while water that later enters because of poor maintenance could be disputed or excluded.
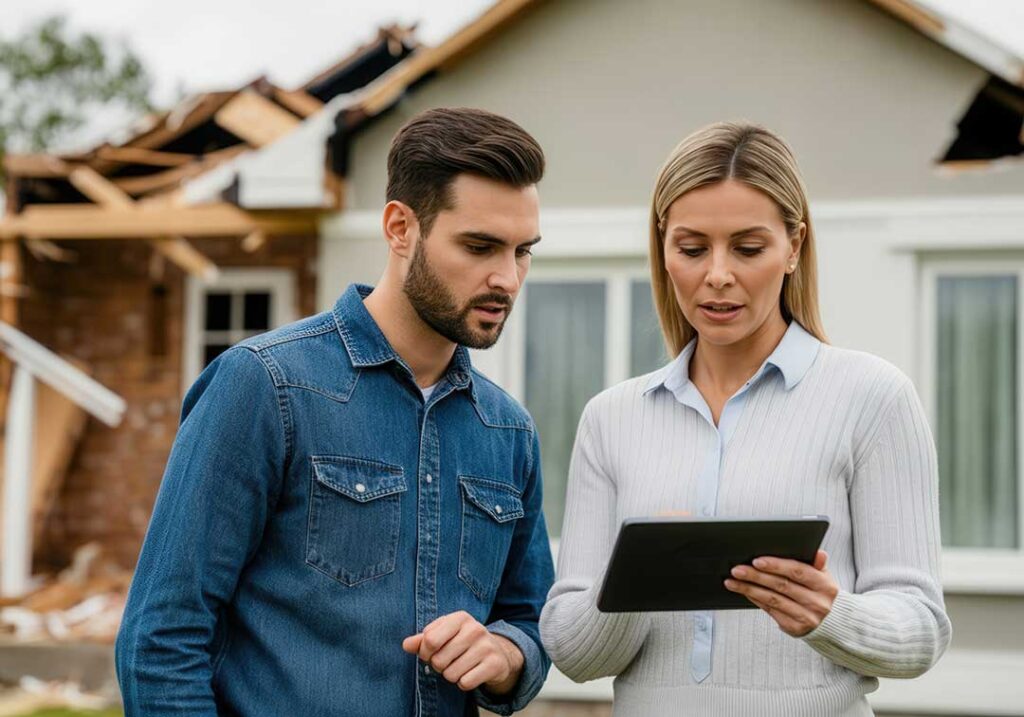
Does homeowners insurance cover tornadoes?
Usually, yes. Tornado damage is generally handled under the policy’s windstorm coverage, subject to the deductible and policy exclusions.
A tornado claim might involve:
- Roof, siding, window, and exterior-wall damage
- Damage from falling trees
- Interior damage caused by rain entering through a storm-created opening
- Damage to personal belongings
- Additional living expenses while covered repairs are completed
The policy may pay for repairs only up to the applicable limits and after the deductible. Detached structures, such as sheds or separate garages, often have their own coverage limit. Trees and landscaping may have restricted coverage, particularly when a tree falls without damaging an insured structure.
Severe thunderstorms in the area can also produce damaging straight-line winds and hail, not only tornadoes. National Weather Service warnings affecting Vestavia Hills have included risks to roofs, siding, and trees from strong winds and hail. ([forecast.weather.gov](https://forecast.weather.gov/product.php?format=TXT&glossary=1&issuedby=BMX&product=SVS&site=NWS&version=29&utm_source=openai))
Does homeowners insurance cover flooding?
Generally, no. Standard homeowners insurance usually excludes damage caused by flooding, even when the flooding follows heavy rain or a severe storm. Separate flood insurance is typically needed for water that rises from the ground and enters the home.
Flood insurance may apply to situations involving:
- Overflow from a creek, drainage channel, or other waterway
- Surface water accumulating on normally dry land
- Flash flooding after intense rainfall
- Mudflow meeting the policy’s definition of flood
- Water entering through doors, walls, or foundations because of surrounding flood conditions
Flood coverage is not limited to homes located in areas commonly described as high-risk flood zones. Flooding can occur outside mapped high-risk areas, and standard homeowners insurance does not become flood coverage merely because a property has never flooded before. The National Association of Insurance Commissioners states that flood damage is not covered by a standard homeowners policy and that separate flood insurance is available through the National Flood Insurance Program and other sources. ([content.naic.org](https://content.naic.org/insurance-topics/flood-insurance?utm_source=openai))
What is the difference between flood damage and wind-driven rain?
The distinction can affect whether the homeowners policy or flood insurance responds.
If wind damages a roof, window, or exterior wall and rain enters through that newly created opening, the resulting damage may be treated as windstorm damage. Alabama Department of Insurance guidance specifically distinguishes wind-driven rain entering through storm-created openings from flood damage. By contrast, if water rises from the ground and inundates normally dry land, it is generally treated as flooding. ([insurance.alabama.gov](https://www.insurance.alabama.gov/PDF/Consumers/NaturalDisastersGuide.pdf?utm_source=openai))
Photos, videos, weather alerts, repair records, and a clear description of how water entered can be useful when documenting a claim. Do not discard damaged materials before the insurer has had a reasonable opportunity to inspect them, unless leaving them in place creates a safety hazard.
Are earthquakes, landslides, and sinkholes covered?
Not necessarily. Earthquake damage is commonly excluded from standard homeowners policies and may require separate coverage. Landslides and earth movement are also frequently excluded, although the exact wording matters.
Sinkhole coverage requires special attention in Alabama because policies may treat sudden ground collapse differently from gradual settling, erosion, or earth movement. The policy language and any endorsements determine whether investigation or repairs may be covered. A mortgage requirement does not mean these hazards are insured.
Could the policy limit be too low after a total loss?
Yes. The dwelling limit should reflect the estimated cost to rebuild the structure, not simply its market value or the outstanding mortgage balance.
Rebuilding costs can rise because of:
- Construction labor shortages after a regional disaster
- Higher prices for lumber, roofing, wiring, and other materials
- Updated building-code requirements
- Specialized features, masonry, or custom finishes
- Debris removal and demolition
- Difficult access or site conditions
Ask whether the policy uses replacement cost or actual cash value. Replacement cost is intended to help repair or rebuild with comparable materials, subject to policy terms. Actual cash value subtracts depreciation and may leave a much smaller payment for older roofs, flooring, furniture, and appliances.
Alabama Department of Insurance guidance also emphasizes checking whether the home is insured for an adequate percentage of its replacement cost. Underinsurance can affect the amount paid, especially when a policy contains a coinsurance or insurance-to-value provision. ([insurance.alabama.gov](https://www.insurance.alabama.gov/PDF/Consumers/NaturalDisastersGuide.pdf?utm_source=openai))
What overlooked coverage gaps should residents check?
A policy review should go beyond the main dwelling limit. Pay particular attention to:
- Roof settlement: Some policies apply age-based or actual-cash-value treatment to older roofs.
- Wind or hail deductibles: The deductible may be a flat dollar amount or a percentage of the dwelling limit.
- Additional living expenses: Check the dollar limit and time limit if the home cannot be occupied.
- Personal property limits: Jewelry, firearms, collectibles, electronics, and business property may have special sublimits.
- Sewer or drain backup: Water backing up through a drain may require an endorsement and is different from flood coverage.
- Other structures: Fences, retaining walls, detached garages, and sheds may have limited or excluded coverage.
- Ordinance or law coverage: Repairs may need to meet current building requirements that did not apply when the home was built.
- Home inventory: Photos, receipts, serial numbers, and approximate purchase dates can make a contents claim easier to document.
The declarations page shows the principal limits and deductibles, but exclusions and endorsements found elsewhere in the policy can change how those limits apply. ([content.naic.org](https://content.naic.org/article/consumer-insight-understanding-your-homeowners-or-renters-policy?utm_source=openai))
How can a homeowner test whether coverage is adequate?
A practical review can begin with four questions:
1. If the home were destroyed, would the dwelling limit realistically cover rebuilding it?
2. Would a percentage deductible be affordable after a major wind or hail event?
3. Would flood insurance be needed based on the property’s drainage, elevation, nearby waterways, or past flooding—not just the flood map?
4. Could the household replace its belongings and pay temporary living expenses within the policy limits?
Review the policy at least annually and after remodeling, adding a room, purchasing expensive property, replacing the roof, or acquiring a detached structure. Keep a copy of the policy, inventory, receipts, and photographs in a secure location away from the home.
If a claim decision appears inconsistent with the policy, preserve written communications and the claim file. The Alabama Department of Insurance provides a consumer complaint process after a policyholder has first attempted to resolve the issue with the insurer or producer. ([insurance.alabama.gov](https://insurance.alabama.gov/Consumers/FileComplaint.aspx?utm_source=openai))